Form N260 is the model statement of costs for summary assessment (PD 44 para 1.2): the signed schedule a party files and serves so that the judge at a fast track trial, or at a hearing lasting no more than a day, can fix its costs there and then instead of sending them to detailed assessment under Part 47. It can decide thousands of pounds of costs in a few minutes, which is why it should not be the form somebody fills in on the morning of the hearing.
Need the form now? Our free N260 builder fills in the official HMCTS form from your fee earners, hours and expenses, works out the totals and VAT, and gives you the PDF and an Excel version.
Summary assessment compresses everything. The judge may have very little time. There are no Points of Dispute and Replies. There may be one short exchange about rates, hours, counsel and proportionality before a number is written down.
So the schedule has to do more than add up. It has to make the costs easy to follow, easy to justify and hard to reduce without a reason.
What Form N260 actually is
Form N260 is the HMCTS Statement of Costs for summary assessment — the procedure where the judge who heard the case or application fixes the recoverable costs there and then, rather than sending them to detailed assessment under CPR Part 47. Practice Direction 44 identifies it as the model form, and the statement must be filed and served at least 24 hours before most hearings, or two days before a fast track trial. Our free CPR deadline calculator works out the last day to file and serve it before a fast track trial.
Note the wording. PD 44 para 9.5 does not require the official PDF to be reproduced exactly — it says the statement should follow Form N260 as closely as possible, and that it must be signed. That leaves room for a clearer schedule where the case needs one, provided the structure and the information the court expects survive. Our guide to the costs forms and precedents sets the N260 alongside the other forms used in costs work, and our free N260 statement of costs builder fills in the official form from your figures.
Take the current form from GOV.UK rather than an internal copy. The published version is maintained, and an old precedent sitting in a firm’s template folder is the usual source of a schedule missing a field the court now expects.
Is there an Excel or Word version of N260?
HMCTS publishes Form N260 on GOV.UK as a PDF only; there is no official Word version. Our free N260 builder fills in that official PDF online, and an editable spreadsheet version is available from the same page. The judiciary has also produced a bespoke Excel N260, but it is for the Rolls Building courts covered by the 2026 Practice Note described below, not for summary assessments generally.
How to complete Form N260, section by section
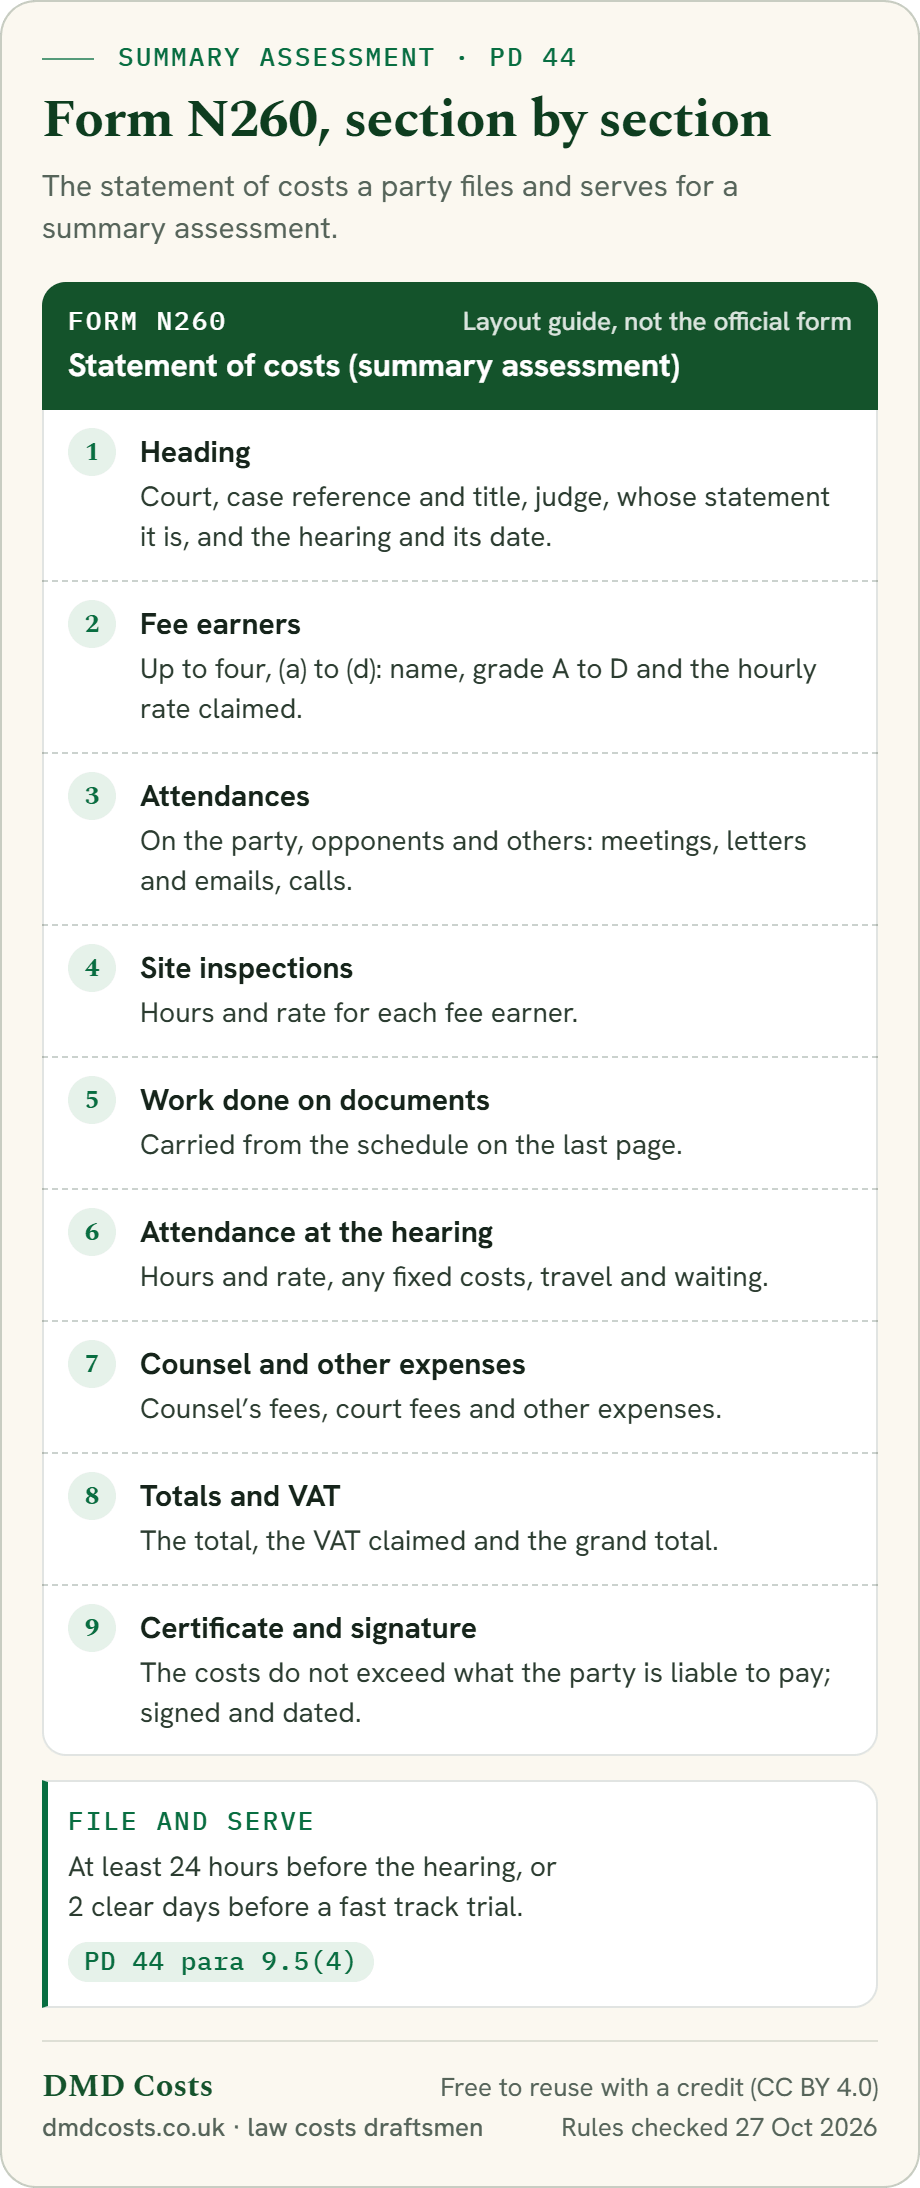
Form N260, the statement of costs for summary assessment, covers, in order: the heading; up to four fee earners with their grade and hourly rate; attendances; site inspections; work done on documents; attendance at the hearing; counsel and other expenses; totals and VAT; and a signed certificate that the costs do not exceed what the party is liable to pay. It must be filed and served at least 24 hours before the hearing, or 2 clear days before a fast track trial (PD 44 para 9.5(4)).
Free to reuse under CC BY 4.0: credit “DMD Costs (dmdcosts.co.uk)” and link to this page. Download the PNG.
Text version of this diagram
The statement of costs a party files and serves for a summary assessment.
Form N260: Statement of costs (summary assessment). Layout guide, not the official form.
- Heading: Court, case reference and title, judge, whose statement it is, and the hearing and its date.
- Fee earners: Up to four, (a) to (d): name, grade A to D and the hourly rate claimed.
- Attendances: On the party, opponents and others: meetings, letters and emails, calls.
- Site inspections: Hours and rate for each fee earner.
- Work done on documents: Carried from the schedule on the last page.
- Attendance at the hearing: Hours and rate, any fixed costs, travel and waiting.
- Counsel and other expenses: Counsel’s fees, court fees and other expenses.
- Totals and VAT: The total, the VAT claimed and the grand total.
- Certificate and signature: The costs do not exceed what the party is liable to pay; signed and dated.
File and serve: At least 24 hours before the hearing, or 2 clear days before a fast track trial (PD 44 para 9.5(4)).
Rules checked 27 October 2026.
The official form runs to five pages, in this order:
- Heading. The court, case reference and case title, the judge or master, whose statement it is, and the hearing it covers (an interim application or a fast track trial) with its date.
- Description of fee earners. Up to four fee earners, (a) to (d), each with their name, grade and the hourly rate claimed. The definitions of grades (A) to (D) are printed on the form, and they are the same grades the guideline hourly rates use.
- Attendances. Time spent on the party, on opponents (including negotiations) and on others, each split into personal attendances, letters out and emails, and telephone calls, with the hours and rate for each fee earner.
- Site inspections. Hours and rate for each fee earner.
- Work done on documents. Carried from the schedule on the last page, one line per item, with the hours for each grade (A) to (D).
- Attendance at the hearing. Hours and rate for each fee earner, travel and waiting time, and a line for fixed costs.
- Counsel and other expenses. Counsel’s name and year of call, the fee for advice, conference or documents and the fee for the hearing, then court fees and any other expenses with a brief description.
- Totals and VAT. The total, the VAT claimed on solicitors’ and counsel’s fees and on other expenses, and the grand total.
- Certificate and signature. A statement that the costs do not exceed what the party is liable to pay and that counsel’s fees and other expenses have been incurred in the amounts stated, signed and dated, with the name of the partner signing and the firm. PD 44 para 9.5(3) lets a legally aided party, or a party represented by its own employee, leave the certificate out.
The rest of this guide covers what goes into those boxes so that the figures survive the hearing: the deadlines, what the statement must show, rates, VAT and the signature, with a checklist at the end.
What summary assessment is
Summary assessment is the judge who decided the case or application determining the amount payable, without a detailed assessment. CPR 44.1 defines it that way, subject to the limited alternative in CPR 44.6(2). The court considers the costs claimed, hears the objection, and fixes a figure that becomes part of the order.
Because that order states the amount, the money falls due quickly: a party must comply with an order for the payment of costs within 14 days of the date of the judgment or order if it states the amount, or by such other date as the court may specify (CPR 44.7). Where the amount is decided later by detailed assessment under Part 47, the 14 days run instead from the date of the certificate which states the amount.
When the court will assess summarily
PD 44 para 9.1: whenever the court makes a costs order which does not provide only for fixed costs, it should consider summary assessment.
Para 9.2 then gives the general rule — the court should ordinarily assess summarily:
- at the conclusion of a fast track trial, dealing with the costs of the whole claim; and
- at the conclusion of any other hearing lasting not more than one day, dealing with the costs of the application or matter determined — or of the whole claim, where the hearing disposes of it.
That is subject to there being good reason not to. PD 44 gives the example: where the paying party shows substantial grounds for disputing the sum claimed which cannot be dealt with summarily. Detailed assessment may then be the better route.
Is an N260 needed on every fast track case?
No — and this is where older guides date badly.
Para 9.1 is about orders which do not provide only for fixed costs. CPR 44.6 separates assessed costs from fixed costs and provides that fixed costs under Part 45 are recovered in accordance with that Part. A fast track trial does not, by itself, mean a conventional N260 is required.
Before preparing one, check:
- whether the claim sits within a fixed recoverable costs regime;
- whether an exception or separate assessed-costs entitlement applies;
- what costs order is actually being sought; and
- whether the court has directed anything specific about costs.
That check belongs in the diary, not in the corridor outside court.
Fixed costs cases: Precedent U, not Form N260
Where the costs claimed are fixed costs or disbursements under Part 45, the statement is a different document. Since 1 October 2024, CPR 45.63(2) has required any party who intends to claim them to file at court and serve a completed Precedent U on any party against whom an order for payment is intended to be sought, no later than 24 hours before the time fixed for the hearing, including, where applicable, the details of any claim under rule 45.9, 45.10 or 45.13. Where the court makes an order for costs at the end of the hearing, it then makes a summary determination of the fixed costs or disbursements, unless the parties have agreed them or the court is unable to do so then (CPR 45.63(1) and (3)). Precedent U is published with Practice Direction 45 as an Excel spreadsheet.
Two differences from the N260 matter. The Precedent U deadline is 24 hours before the hearing; on our reading that includes a fast track trial, where an N260 would need 2 days (PD 44 para 9.5(4)(a)). And CPR 45.63 has no equivalent of PD 44 para 9.6: it does not say what happens if the deadline is missed (see what happens if the statement is late, below). Fast track and intermediate track fixed costs do not apply to a claim that includes a claim for disrepair of a residential property, unless it arises from a boundary dispute (CPR 45.1(4)), so a housing disrepair trial usually needs an N260 rather than a Precedent U.
The deadlines
| Hearing | Latest filing and service (PD 44 para 9.5) |
|---|---|
| Fast track trial | Not less than 2 days before the trial |
| Any other hearing | Not less than 24 hours before the time fixed for the hearing |
The statement must be filed at court and served on every party against whom a costs order is sought, as soon as possible and in any event by those points. They are minimums, not targets. A substantial schedule landing at the cut-off invites objections at the hearing that could have been narrowed by correspondence a week earlier.
What happens if the N260 is late
There is no rule that a late N260 produces nil costs. There is also no version of this where late service is harmless.
PD 44 para 9.6 provides that failure, without reasonable excuse, to comply with para 9.5 will be taken into account by the court in deciding what order to make about costs. So the consequence is discretionary, and depending on the circumstances may be a reduction, an adjournment of the costs issue, directions for later assessment, or costs consequences arising from the further hearing the failure made necessary.
How courts use that discretion comes from Neuberger J’s guidance in Macdonald v Taree Holdings Ltd [2001] 1 Costs LR 147, a case about a schedule of costs served late for a summary assessment. The court takes the failure into account, but its reaction should be proportionate. For a mere failure, the first question is what prejudice it caused the other party; if none, the costs are assessed in the normal way. If there was prejudice, the options include a short adjournment for the paying party to consider the schedule, with the court erring towards a lower figure in case of doubt; standing the costs over for detailed assessment, possibly at the receiving party’s expense for that assessment; or a later summary assessment, often on written submissions (Macdonald at [23]–[25]). In a case of mere failure, Neuberger J did not think it right to deprive a party of its costs altogether (at [26]); with an aggravating factor, such as a deliberate failure after the schedule was asked for in time, all or a significant proportion of the costs may be lost (at [27]). Courts still apply it: in November 2026 a County Court appeal followed Macdonald for a fixed costs statement served about 19 hours before trial instead of 24, as our note on Ashi v Daniels and the late Precedent U explains.
Neither “miss 24 hours and you lose your costs” nor “it does not really matter” is accurate advice. The way to avoid needing to know which is right is to prepare it early enough that compliance is never in issue.
What the statement must show
PD 44 para 9.5 requires the statement to show separately:
- the number of hours claimed;
- the hourly rate claimed;
- the grade of fee earner;
- the amount and nature of disbursements, other than counsel’s hearing fee;
- the legal representative’s costs of attending or appearing at the hearing;
- counsel’s fees; and
- the VAT claimed.
These are not form-filling fields. They are what the judge needs to assess the claim. A schedule that makes the court work out who did the work, at what rate, or what an unexplained disbursement represents, has made summary assessment harder than it needed to be — and the party who prepared it carries the cost of that.
The block figure problem
This is where N260s are most often vulnerable. A single line reading:
“Work done on documents — £4,850”
gives the judge nothing to assess and every reason to apply a broad reduction. Depending on the hearing, the underlying work might be reviewing the application and evidence, preparing evidence in response, considering witness statements or disclosure, instructions to counsel, considering authorities, preparing the bundle, reviewing offers and preparing for the hearing.
An N260 does not need to become a chronological bill. But there is a wide gap between a sensible summary and an unexplained block, and summary assessment still requires enough detail for the court to assess.
Hourly rates and the 2026 guidelines
Rates are the most common flashpoint. The 2026 Guideline Hourly Rates took effect on 1 January 2026, and they matter here more than anywhere because summary assessment is the context the guidelines came from.
They are not automatic entitlements and not a ceiling. The court still weighs grade, location, complexity, skill and responsibility, the nature of the work, the time spent and the rest of the CPR 44.4 factors. Where the rate exceeds the applicable guideline, expect to be asked why.
And note the separate challenge: the grade can be attacked even where the rate matches the guideline exactly, if a senior fee earner did routine work. That argument runs the same way at summary assessment as it does on a bill — the reasoning is set out in our guide to defending senior fee earner rates against a delegation challenge.
Standard basis or indemnity basis?
An N260 is a format. It does not decide the basis of assessment.
Under CPR 44.3, summary assessment can be on either basis, and where the order does not specify, it is the standard basis.
| Standard basis | Indemnity basis | |
|---|---|---|
| Proportionality | Applies | Does not apply in the same way |
| Doubt resolved in favour of | The paying party | The receiving party |
| Costs must still be | Reasonable and proportionate | Reasonably incurred and reasonable in amount |
That difference can be worth a great deal on the same schedule, so prepare the N260 with the order actually being sought in mind. Where an indemnity order is in play because of an offer, the mechanics matter — and they are narrower than often assumed, as our note on when Part 36 actually shifts the basis of costs explains.
What the judge is weighing
CPR 44.4 requires the court to have regard to all the circumstances, including:
- the conduct of the parties, and efforts made to resolve the dispute;
- the amount or value involved;
- the importance of the matter;
- complexity or novelty;
- skill, effort, specialised knowledge and responsibility;
- time spent;
- where and in what circumstances the work was done; and
- the receiving party’s last approved or agreed costs budget.
Which is why presenting 20 hours × £295 = £5,900 does not answer the assessment. The question is whether the time, the rate and the work were reasonable in this dispute.
Costs budgets and the N260
CPR 44.4 lists the last approved or agreed budget among the matters the court considers. On a costs-managed case, whoever prepares the N260 needs to know whether the work is incurred or budgeted, which phase it falls in, what the budget allows and whether anything in the costs-management history is likely to come up.
Budgeting is reaching into cases that once sat outside it — the High Court ordered it in £10m-plus group litigation in Fuschillo v Johnson & Johnson — so the assumption that a given file is unbudgeted is worth checking rather than making.
VAT: do not simply add 20%
PD 44 is specific about this and it is regularly got wrong.
- Where VAT is claimed, the receiving party’s VAT registration number must appear in a prominent place at the head of the statement (para 2.2).
- VAT should not be included in a claim for costs where the receiving party is able to recover it as input tax (para 2.3).
- Where only part is recoverable as input tax, only the irrecoverable proportion should be claimed.
So the sequence is not “profit costs, then add VAT”. It is “what is this client’s VAT position”, and the responsibility for getting it right sits with the receiving party.
Counsel, travel and waiting
Counsel’s fees belong in their own lines — advice, conference, document work and the hearing fee. For the hearing fee the court may consider whether attendance was reasonably required and whether the amount is reasonable. Where counsel did substantial preparatory work, make that visible rather than presenting one unexplained figure, and make sure the schedule matches the fee note.
Travel and waiting have their own fields. Recorded time is not the same as recoverable time, and a claim should be checked against the actual hours, the rate applied and the circumstances of the hearing.
Why the signature matters more than it looks
The statement must be signed by the party or their legal representative, and PD 44 applies the Part 22 rules about who may sign as though the document were a statement of truth.
The certificate on the form goes further. The person signing certifies, in substance, that:
- the costs stated do not exceed the costs the party is liable to pay; and
- counsel’s fees and other expenses have been incurred in the amounts stated and will be paid to the people identified.
That ties the N260 directly to the indemnity principle. It is a signed costs document, not an opening position. Where there is a live question about the retainer, the client’s liability or a disbursement, resolve it before signing — the consequences of an entitlement that fails underneath a costs claim are set out in HD v North Devon Healthcare Trust, where unenforceable retainers took six assessments to nil.
Costs schedule, schedule of costs or statement of costs?
They are the same document. PD 44 para 9.5(2) requires each party claiming costs to prepare a written statement of those costs “in the form of a schedule”, which is why orders and letters say “costs schedule” or “schedule of costs” while the rules and the form say “statement of costs”. Whatever the order calls it, Form N260 is what the court expects, signed and served in time. Statements of costs are needed wherever the court is likely to assess costs summarily: at the end of a fast track trial and of any other hearing lasting no more than a day (PD 44 para 9.2), not only at trial.
Two things with similar names are different. In family proceedings the statement of costs for a final hearing is Form H1, not an N260 (FPR 9.27(4)); our free Form H and H1 builder fills that in. And the schedule to a Tomlin order is the settlement terms annexed to the order, not a schedule of costs.
N260 or Bill of Costs?
| N260 | Bill of Costs |
|---|---|
| Summary assessment | Detailed assessment under Part 47 |
| Usually determined by the hearing judge | Assessed by a costs judge or officer |
| Condensed schedule | Substantially more detail |
| Often one application or short hearing | Can cover the whole entitlement |
| May be assessed immediately | Its own procedural timetable |
| No Points of Dispute and Replies stage | N252, Points of Dispute, Replies, assessment |
An N260 should be detailed enough to permit a proper assessment without being drafted as an electronic bill. Where the costs go the other way instead, the detailed assessment route has its own traps — including what happens when Points of Dispute are defective — and where the substantive claim settled without proceedings, CPR 46.14 costs-only proceedings may be the route to assessment at all.
The 2026 Rolls Building change
This is the update missing from most N260 guides still in circulation.
From 14 April 2026, a Practice Note applies to summary assessments in the Chancery Division (since 1 October 2026 the Business and Property Division), the Technology and Construction Court, the Commercial Court and the London Circuit Commercial Court, within the Rolls Building. For those assessments, parties should file and serve an Excel version of N260 in addition to a signed read-only PDF.
The bespoke Excel replicates N260, uses self-calculating formulae and accommodates up to twelve solicitors and two counsel.
One point to carry: the April note superseded an earlier note of 13 March 2026, which had directed parties to pilot forms N260A and N260B. Any process built on the March version needs updating, and any guide still describing N260A/N260B as the requirement is out of date.
The ordinary PD 44 filing and service deadlines continue to apply.
It does not apply everywhere
The Practice Note is expressly limited to those courts within the Rolls Building. It is not a nationwide replacement for the ordinary N260 process, and presenting it as one is the sort of error a paying party enjoys correcting.
If the paying party disputes it heavily
A substantial dispute does not automatically defeat summary assessment, but para 9.2 recognises there may be good reason not to assess summarily where the paying party shows substantial grounds that cannot be dealt with in the time available. The court can order detailed assessment instead, and under CPR 44.6 can direct that summary assessment happen later.
Which is an argument for transparency rather than compression: a schedule clear enough that legitimate objections can be resolved in minutes is a schedule that gets assessed rather than adjourned.
Can a costs officer pick it up later?
Not simply because the judge ran out of time. PD 44 para 9.7 is explicit that the court awarding costs cannot order a summary assessment by a costs officer. Where summary assessment remains appropriate but cannot be completed, the court can give directions for a later hearing, and CPR 44.6(2) allows another judge who could have decided the underlying matter to carry it out where there is good reason. That is a different thing from sending the costs for detailed assessment.
Where N260s actually get reduced
The vulnerable areas are predictable, which is what makes them avoidable:
- Excessive preparation time — why did this application need those hours?
- Senior fee earners on routine work — correct grade does not make every attendance reasonable.
- Above-guideline rates with no explanation — give the court a reason before it asks.
- Duplication — two fee earners on the same issue needs justifying.
- Large blocked document time — the less the judge can see, the broader the cut.
- Unexplained counsel’s fees — identify the work and match the fee note.
- Unsupported disbursements — have the invoices to hand.
- Incorrect VAT — check entitlement rather than adding it automatically.
- Work outside the application — an interim schedule should not quietly carry costs of the wider action.
- Disproportionate totals — individually reasonable work can still be cut on the standard basis.
Note too that agreement does not save a figure: para 9.10 provides that the court will not approve disproportionate or unreasonable costs, and where costs are agreed the order should record that it is by consent.
Prepare it backwards
The strongest schedules are built from the argument that is going to happen. Ask what the paying party will attack.
- Rates? Make the grades and periods unmistakable.
- Preparation time? Show what generated it.
- Counsel? Have the fee note.
- Proportionality? Know what drove the spend.
- Duplication? Make supervision distinguishable from repetition.
- Budget? Know the approved position.
- VAT? Know the client’s status.
An N260 should answer the obvious objections before the advocate has to answer them out loud.
Checklist before it goes out
- Is summary assessment actually appropriate, and is the case fixed-costs only?
- Is the correct hearing and date shown, and does the schedule cover the right costs period?
- Has the 2-day or 24-hour deadline been diarised?
- Are all fee earners identified and correctly graded, with current, defensible rates?
- Can any above-guideline element be explained?
- Is document time broken down, and are attendance costs separated?
- Are counsel’s fees accurate and disbursement invoices available?
- Is VAT properly recoverable, and is the registration number shown?
- Has any approved or agreed budget been considered?
- Does the total reconcile, and does it stay within the client’s underlying liability?
- Has the right person signed it?
- If the hearing is in a Rolls Building court covered by the 2026 Practice Note, are both the Excel N260 and the signed PDF ready?
The last question is the only one that matters: could the advocate defend this schedule if the judge went through it line by line now? If not, it is not finished. The wider sequence from order to payment is set out in our costs recovery checklist.
How DMD Costs can help
We prepare N260 Statements of Costs for claimant solicitor firms dealing with interim hearings, applications and other matters where summary assessment is expected — reviewing the recoverable period, fee earner grading, rates, document and preparation time, counsel’s fees, disbursements, VAT, proportionality and budget alignment, and making the schedule assessment-ready for whoever is on their feet.
We provide drafting support rather than advocacy; the instructing solicitor or advocate remains responsible for the hearing. The distinction between the drafting and advocacy roles is set out in our note on what a costs draftsman does and what a Costs Lawyer does.
N260 needed for an upcoming hearing? Send us the file and the hearing details and we will confirm the fixed fee before any work begins. Our full range of costs drafting services covers everything from a single schedule to detailed assessment.
Key takeaways
The form is short. The assessment behind it is not. The strongest N260s get five things right:
- Scope — know which costs the hearing actually concerns.
- Deadline — 2 days for a fast track trial, 24 hours otherwise, and earlier is better.
- Rates — correct grades, current rates, and a reason for any departure.
- Evidence — counsel’s fee note, disbursement invoices, VAT position.
- Presentation — clear enough that the judge need not reconstruct the file in court.
Get those right and the N260 stops being a form and starts being a costs recovery document.
A note on sources
Written from the primary material: Practice Direction 44, in particular paragraphs 2.2, 2.3, 9.1, 9.2, 9.5, 9.6, 9.7 and 9.10; CPR 44.1, 44.3, 44.4, 44.6 and 44.7; CPR 45.1(4) and 45.63 and Precedent U in Practice Direction 45; Macdonald v Taree Holdings Ltd [2001] 1 Costs LR 147, which we have not found in a free official source and which is set out at [23]–[27] in Whittaker v Bertha UK Ltd [2023] EWHC 2554 (Ch) at [77]; the Guideline Hourly Rates 2026, in force 1 January 2026; the official Form N260 published by HMCTS; and the Rolls Building Practice Note on summary assessments effective 14 April 2026, which superseded the note of 13 March 2026 that had referred to pilot forms N260A and N260B.
Sources
- Practice Direction 44: General Rules about Costs (Section 9: summary assessment and the statement of costs).
- CPR Part 44: General Rules about Costs (rule 44.6: procedure for assessing costs; rule 44.7: time for complying with an order for costs).
- CPR Part 45: Fixed Costs (rule 45.63: summary determination after hearing and Precedent U), with Practice Direction 45 (Precedent U).
- Form N260, statement of costs for summary assessment (GOV.UK)